
With wetter weather becoming a regular occurrence and claims for flood damage on the rise, our customers regularly ask our teams: “Am I insured if I drive through flood water?”
This blog looks at what type of insurance is most likely to cover vehicle flood damage, what damage flood water can do, and what you need to file a claim for damage to your vehicle.
Are you insured if you drive through flood water?
Insurers divide flood damage into two categories, so let’s explore flood damage from an insurer’s point of view.
- Avoidable flood damage
- Unavoidable flood damage
Avoidable flood damage
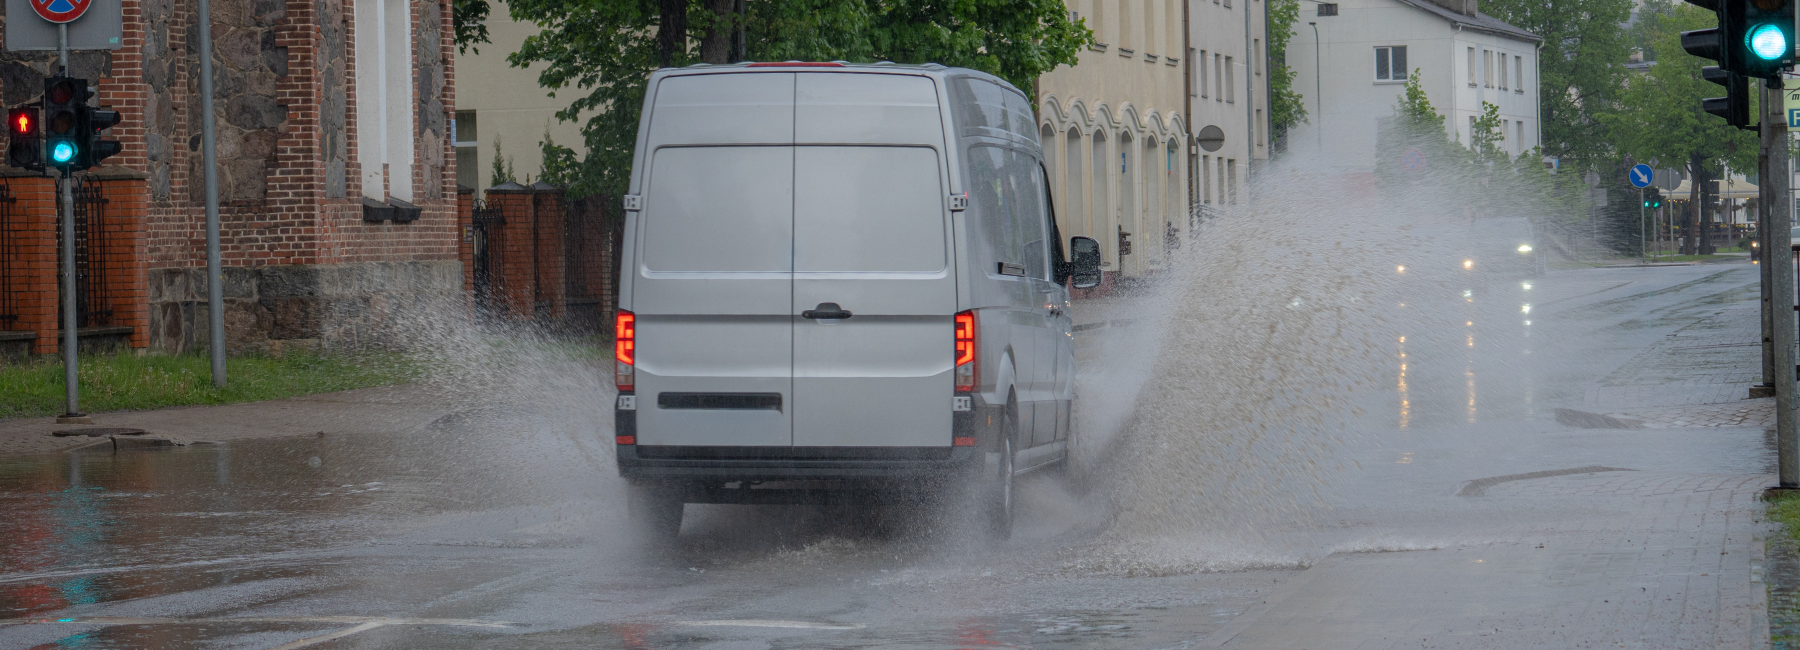
If you drive through flood water, ignore clear flood warnings, and damage your vehicle, your insurance claim might not be paid. If you could have turned around or avoided the flooded area in any way, the flood damage could be seen as “avoidable” by the insurer.
Unavoidable flood damage
If a flood occurs at your home or in the location you park your vehicle overnight and there is no way of avoiding the floodwater, or you are caught in a flash flood, your insurer will usually consider this to be “unavoidable” and will be more likely to uphold an insurance claim for flood damage to your vehicle.

What insurance covers flood damage to vehicles?
The type of insurance cover you have for your vehicle can have an impact on whether you are insured if your vehicle suffers flood damage. There are three main levels of vehicle insurance:
- Comprehensive cover
- Third-party, Fire and Theft (TPFT)
- Third-party only (TPO)
Does fully comprehensive insurance cover flood damage?
Fully comprehensive Van Insurance (or Car Insurance) provides the highest level of protection and is the only standard policy type that routinely covers water damage to your own vehicle caused by flooding.
If your van or car is submerged or suffers water-related mechanical or electrical damage, a comprehensive policy will usually cover repair costs or, in severe cases, the total loss of the vehicle.
However, it is important to remember that if your insurer thinks the flood damage was avoidable (for example, you drove through floodwater in a rush to make a delivery on time and it was deeper than you thought), they might not pay out for a claim.
Third Party, Fire and Theft (TPFT)
This level of insurance covers you for damage or injury to a third-party or their property (i.e. damaging their vehicle in a road traffic incident). It also insures you if your vehicle is damaged from fire or stolen. TPFT will not cover your vehicle for flood damage, and you will need to cover the cost of repairs or replacements yourself.
Third-party only (TPO)
Third Party Only insurance is the minimum legal requirement in the UK and provides the most limited level of cover.
It protects you against:
- Injury to other people
- Damage to third-party property
It does not cover any damage to your own vehicle, whether caused by accidents, theft, fire, or flooding.
In the context of flood damage, this means:
- You would receive no compensation for damage to your own vehicle
- You would be fully responsible for repair or replacement costs
If you’re not sure as to which type of Van Insurance you have, or whether your Courier Insurance covers you for “unavoidable flood damage” talk to the BCD team. We can help you understand what you’re covered for and provide advice on what to do should you need to make an insurance claim for flood damage to your van or car. We can also give you a free, no-obligation Courier Insurance quote which will keep you covered at the right level.
What damage can flood water do to your vehicle?
Floodwater can cause extensive and often hidden damage to a vehicle, affecting both mechanical and electrical systems.
- Engine – if water enters the air intake, it can lead to “hydro lock,” where the engine seizes because water cannot be compressed like air. This often results in severe, sometimes irreparable damage.
- Electrical systems – vulnerable to damage when exposed to water. Modern vans and cars have complex wiring, sensors, and control units, all of which can short-circuit or corrode when exposed to water. This might not be immediately obvious and can lead to ongoing faults weeks or months later. If your vehicle seems to be OK after driving through floodwater, it’s still best to check for corrosion or rust a few weeks or months after the wet weather season in case damage has set in.
- Battery and onboard electronics – the battery, Sat Navs, music systems, and dashboard controls may fail after water exposure.
- Fuel system – water entering the fuel tank can disrupt engine performance and cause long-term issues.
- Interior components – carpets, upholstery, and insulation can become waterlogged. This often leads to mould, unpleasant odours, and deterioration over time. Safety features like airbags and braking systems can also suffer damage if water reaches critical sensors.

Can you drive electric vehicles through flood water?
Electric vehicles can drive through shallow flood water, but they should not be treated as immune to water damage. Flood water can still create serious risks if it is deep, fast-moving, or prolonged. Aspects to consider are water depth, vehicle speed, and current. Even if the battery pack on your vehicle is sealed, water entering connectors, charging ports, sensors, brakes, wheel bearings, or cabin electronics can cause faults or corrosion later.
After driving through flood water, EV owners should inspect the vehicle carefully. Warning lights, reduced performance, unusual noises, or charging problems may indicate hidden damage. Manufacturers often advise professional inspection if water reaches the battery area or enters the cabin.
What should you do after driving through flood water?
If your vehicle is affected by flooding, it’s important to act quickly when checking your vehicle and making an insurance claim.
- Check the brakes immediately: At low speed, gently apply the brakes several times to confirm they respond normally and to help dry brake components. If braking feels weak or uneven, stop driving and seek inspection.
- Look for warning lights or faults: Watch the dashboard for battery, engine, ABS, traction control, or electrical warnings.
- Listen and feel for unusual behaviour: Note any grinding noises, vibration, steering heaviness, hesitation, or reduced power, which can indicate water damage to bearings, belts, sensors, or electronics.
Steps to take when making an insurance claim
- Notify your insurer as soon as possible.
- Avoid starting the vehicle. Doing so may worsen the damage.
- Document the situation thoroughly. Take photos of the vehicle, water levels, and surrounding area. This can help support your claim and can lead to a faster resolution.
- Follow your insurers instructions. They may arrange for an inspection or ask you to take the car to an approved repairer.
- Provide any requested documentation promptly. This includes details of the incident and ownership records.
- Understand your coverage. If your policy includes comprehensive cover, you may be eligible for repairs or a total loss settlement, depending on the extent of the damage.
Why choose Business Choice Direct?
You can’t control the weather, but you can take the right steps to protect your courier business and your vehicle. Stay safe. Talk to our team to ensure you get the right level of Courier Insurance. Get insured with BCD today.